
Higher Yields, Higher Bitcoin
· Macro Analysis · Stormrake
- BTC
- PAXG
Real Yields Just Hit an 18-Year High. Bitcoin Didn't Flinch.
The Fed raised rates on Wednesday last week. The FOMC voted 12-0 to lift the target range by a quarter point to 3.75% to 4%, noting that economic activity is expanding at a solid pace and that inflation remains elevated. First increase since July 2023.
Bitcoin sold off into it, traded down to around $75,000, and has spent the days since climbing back toward $81,000.
That is the part worth sitting with. Not the hike. The response to it.
The Number Nobody Is Talking About
Forget the funds rate for a second. The more important print came the day after the meeting.
The Treasury’s 10-year TIPS reopening on 17 September cleared at a real yield of 2.653%, the highest in nearly 18 years. The nominal 10-year had briefly pushed above 5% earlier that week before settling back near 4.93%.
Real yields are the actual competition for any asset that pays you nothing to hold it. And they are now at levels last seen in the wreckage of 2008.
Here is what makes it stranger. Subtract the real yield from the nominal and you get an implied inflation breakeven of roughly 2.3%. The bond market is not pricing runaway inflation. It is demanding a historically large real return to lend to the US government for a decade. That is a story about government borrowing and term premium, not about CPI.
Why This Should Not Be Working
The textbook is unambiguous. Higher real yields raise the opportunity cost of holding a zero-yield asset. Money should leave Bitcoin and gold, and go collect 2.65% above inflation, with little credit risk, from the US Treasury.
It is not happening. Gold fell more than 1% on the 16th on the hawkish tone and a stronger dollar, then buyers returned and it closed the week near $4,378. Bitcoin did the same thing with a bigger bounce.
And this is not a market that has been told the tightening is over. Sixteen of the eighteen FOMC participants expect another rate increase, with four of them seeing two more as possible. Markets are pricing roughly a 53% probability of another move in October.
We walked through the 10-year in detail last week and the conclusion has not changed. Going back to the 1960s, the yield has risen an average of 114 bps in the first 12 months of a hiking cycle. Repeat that from here and you are looking at 6%, a level not seen since 2000. We have made the long-term counter argument plenty of times, that the 6% is paid in a currency losing purchasing power by a government carrying more than US$40 trillion in debt. All true. But in the short term a risk-free 6% is going to look appealing to a lot of allocators, and that is a headwind worth respecting rather than waving away.
So the setup is: rates are higher, rates are projected higher still, real yields are at an 18-year peak, and both the old and the new age non-yielding assets are bid. The younger of the two is leading the charge.
Three Explanations, One Of Which Holds Up
It was priced in. Partly true and mostly boring. Bitcoin weakened into the decision, so some of the risk was discounted beforehand. But positioning explains a bounce off $75,000. It does not explain a run at the top of the range with the dot plot pointing higher.
The ETF bid is absorbing it. This is the popular answer and it needs scrutiny. US spot Bitcoin ETFs recorded roughly $746 million in net outflows between 15 and 16 September. The structural bid did not show up for this one. And the broader record is not what the marketing says. In the first half of 2026, Bitcoin ETFs saw cumulative net outflows of $5.29 billion as the price fell from $94,000 in January to $63,000 in May. The institutional bid did not prevent the drawdown. It participated in it.
The market is repricing the sovereign, not the rate. This is the one that survives contact with the data. If yields were rising because inflation expectations were rising, you would see it in breakevens. You do not. What you see is investors demanding a much higher real return to fund a government that keeps borrowing. When the risk-free asset starts being priced as if it is not quite risk-free, assets outside that system get a bid, regardless of what the policy rate does.
That is the same reason gold is holding. Bitcoin is trading as the high-beta expression of it.
What It Still Needs To Prove
None of this is confirmed yet. The $83,000 area has turned price back four times since August, and a clean break is what turns a resilient range into a trend. Flows cut both ways too. Net flows into US spot Bitcoin ETFs in 2026 are still roughly negative $1 billion, which means the institutional bid has been thin, but also that there is room for it to return.
But look at what the market has just absorbed. A first hike since 2023, guidance pointing to more, real yields at an 18-year high and three quarters of a billion dollars of ETF outflows in two days. The last time the Fed ran a tightening cycle, Bitcoin fell 77%. This time it held its ground and bounced.
Stop watching the Fed and start watching the long end. The funds rate is a decision. The 10-year is a verdict.
Stormrake Spotlight: Pax Gold (PAXG) ($4,364)
Source: https://www.tradingview.com/x/qWv1o3CW/
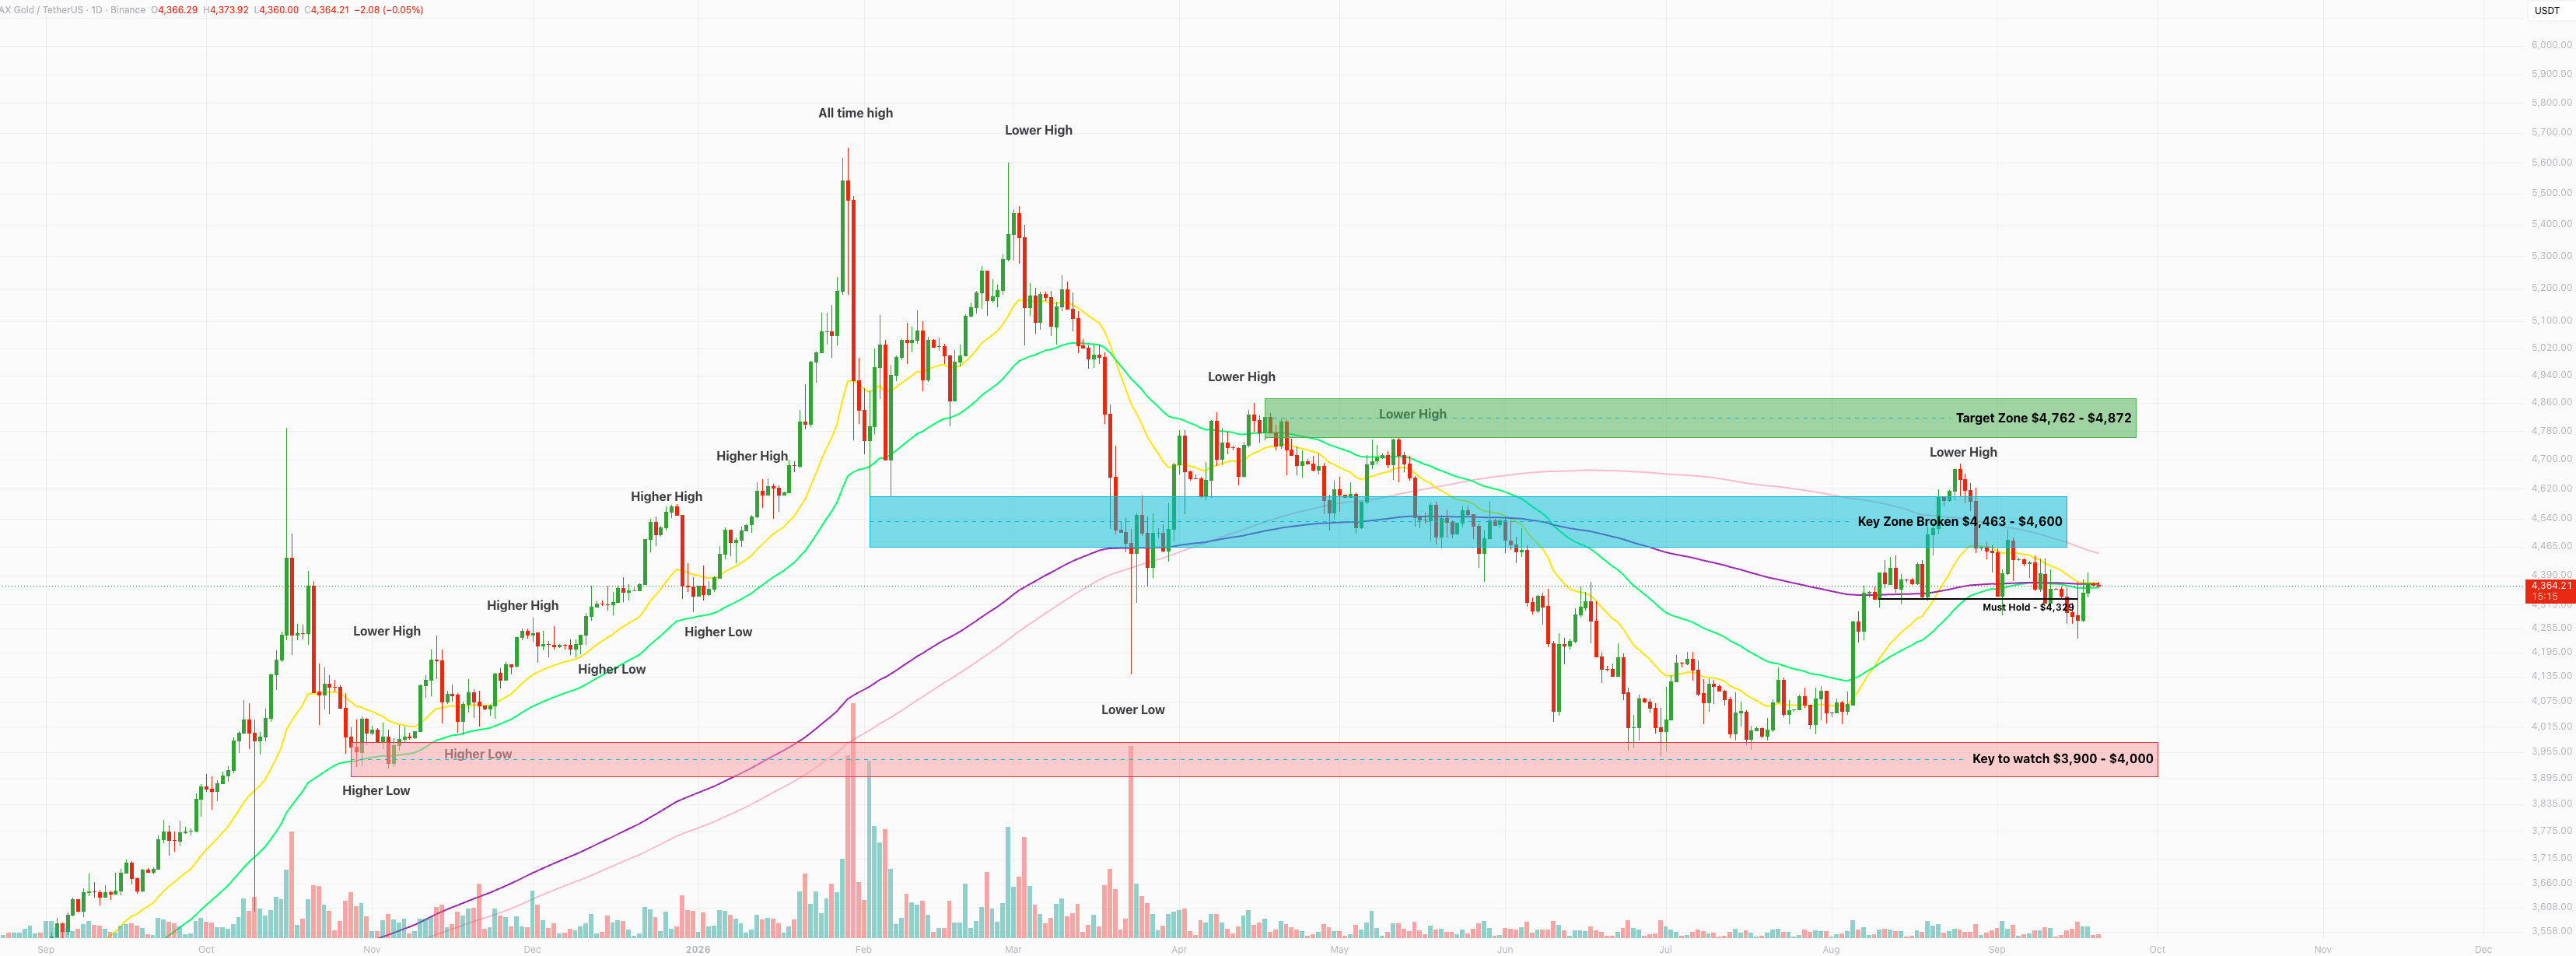
PAXG had a strong end to last week following the Fed hike, a welcome surprise given higher rates are meant to weigh on gold. In doing so, it has flipped momentum back in favour of the bulls. It is the old-world half of this morning’s story.
As trading resumes, this looks to be a decisive week. PAXG is consolidating right on top of all its moving averages, and that tends to resolve one of two ways: a bounce higher, or a rejection that sends it lower.
BTC/USD Key Levels and Price Action:
Source: https://www.tradingview.com/x/quDO4ken/
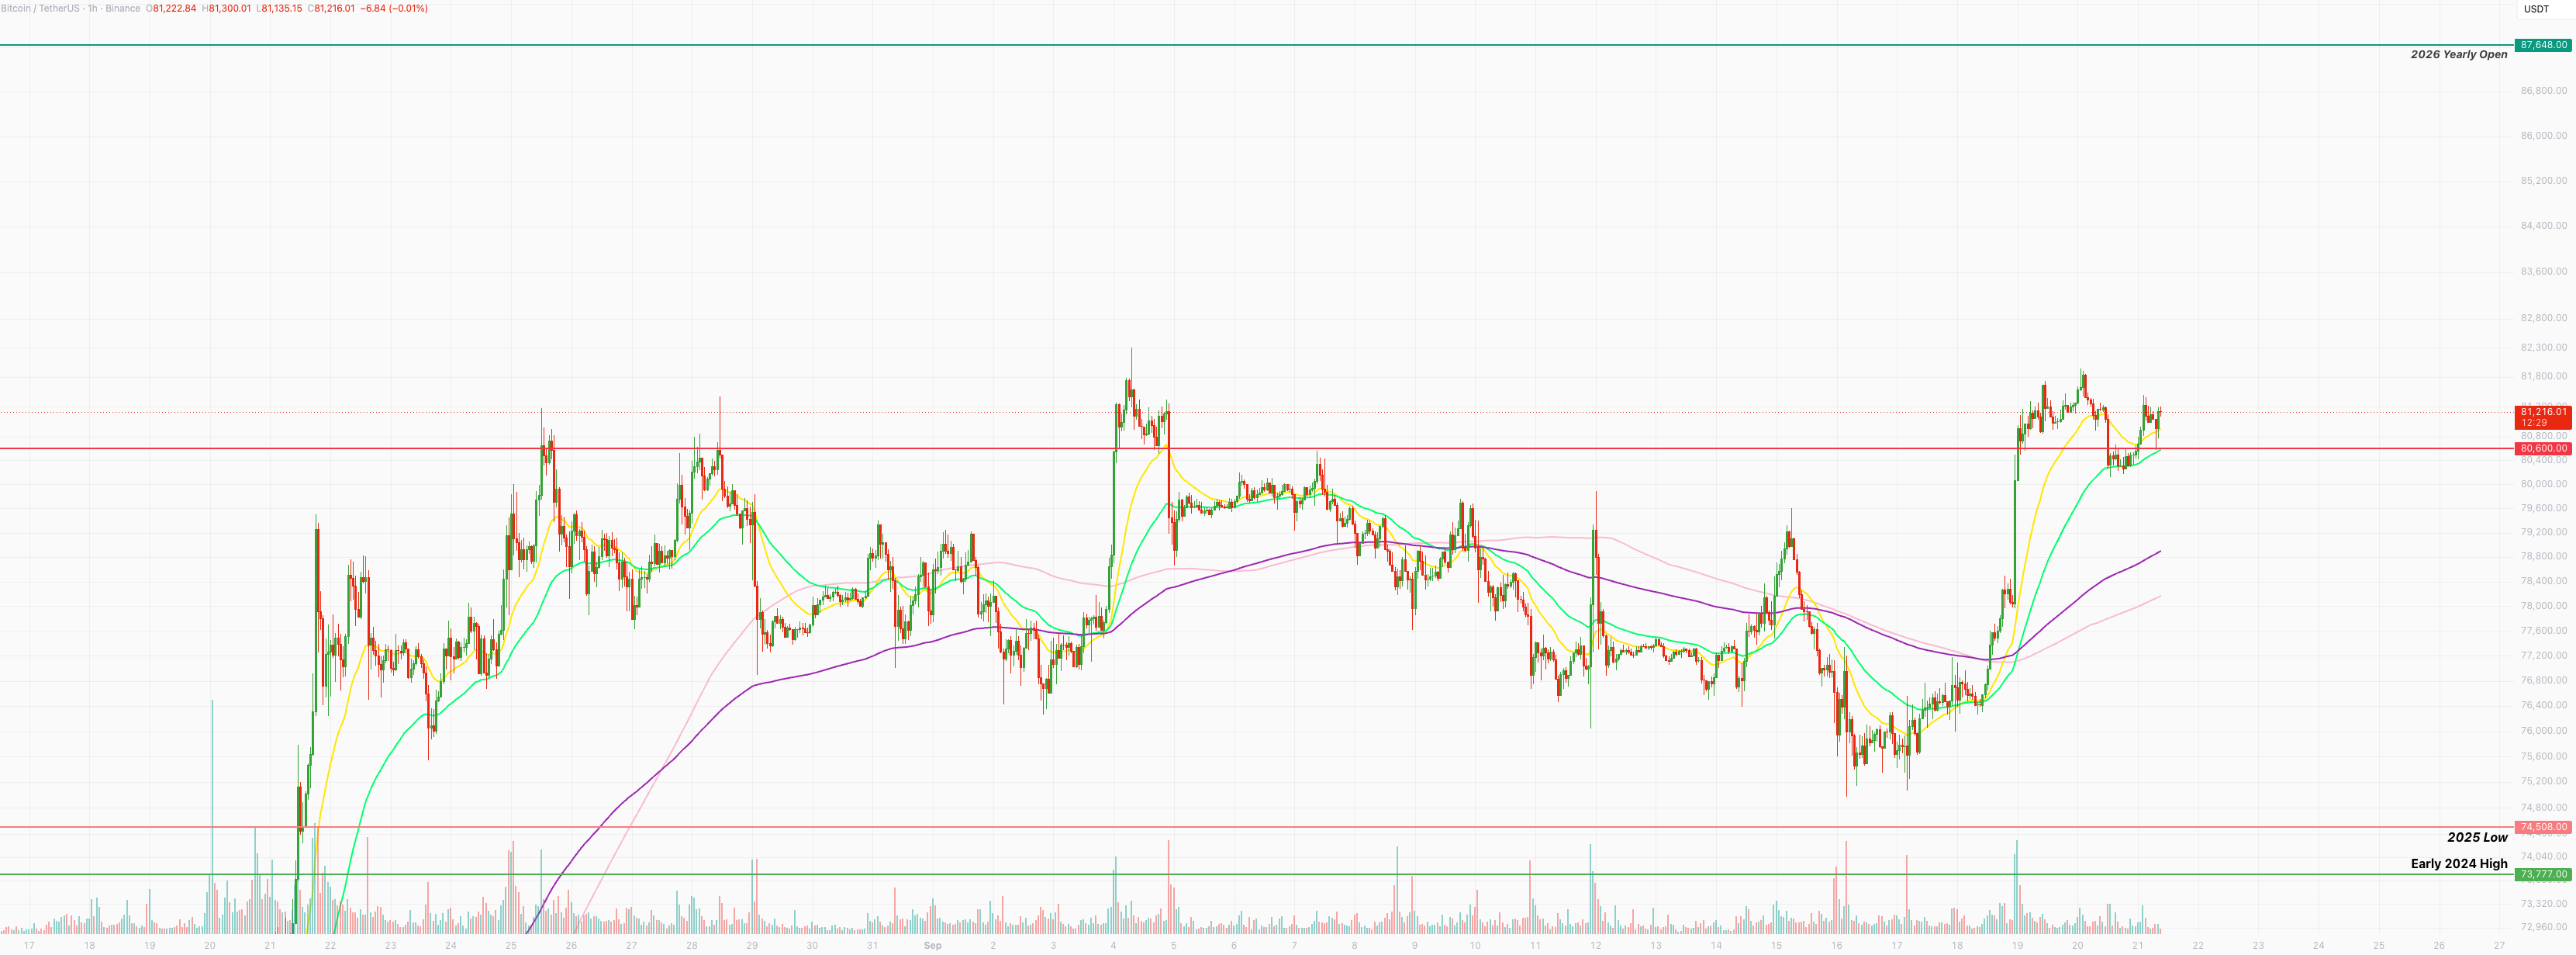
Bitcoin has flipped the key $80.6k level into support, with the moving averages now sitting at the same level to strengthen it further. Holding here would mark the first sustained break above this price since the August rally. The overhead at the much discussed $83k still remains a real challenge.
*All prices are denominated in USD unless stated otherwise*
Written by Alexandar Artis
Disclaimer
This information is general in nature and does not take into account your personal objectives, financial situation, or needs. Before acting, you should consider whether this information is appropriate for your circumstances and seek independent advice if necessary.
Digital assets are volatile and carry significant risk. Past performance is not indicative of future results. You may lose some or all of your investment.